Measured per group of contracts, and it has to add up
Ifrs 17, Premium Allocation Approach
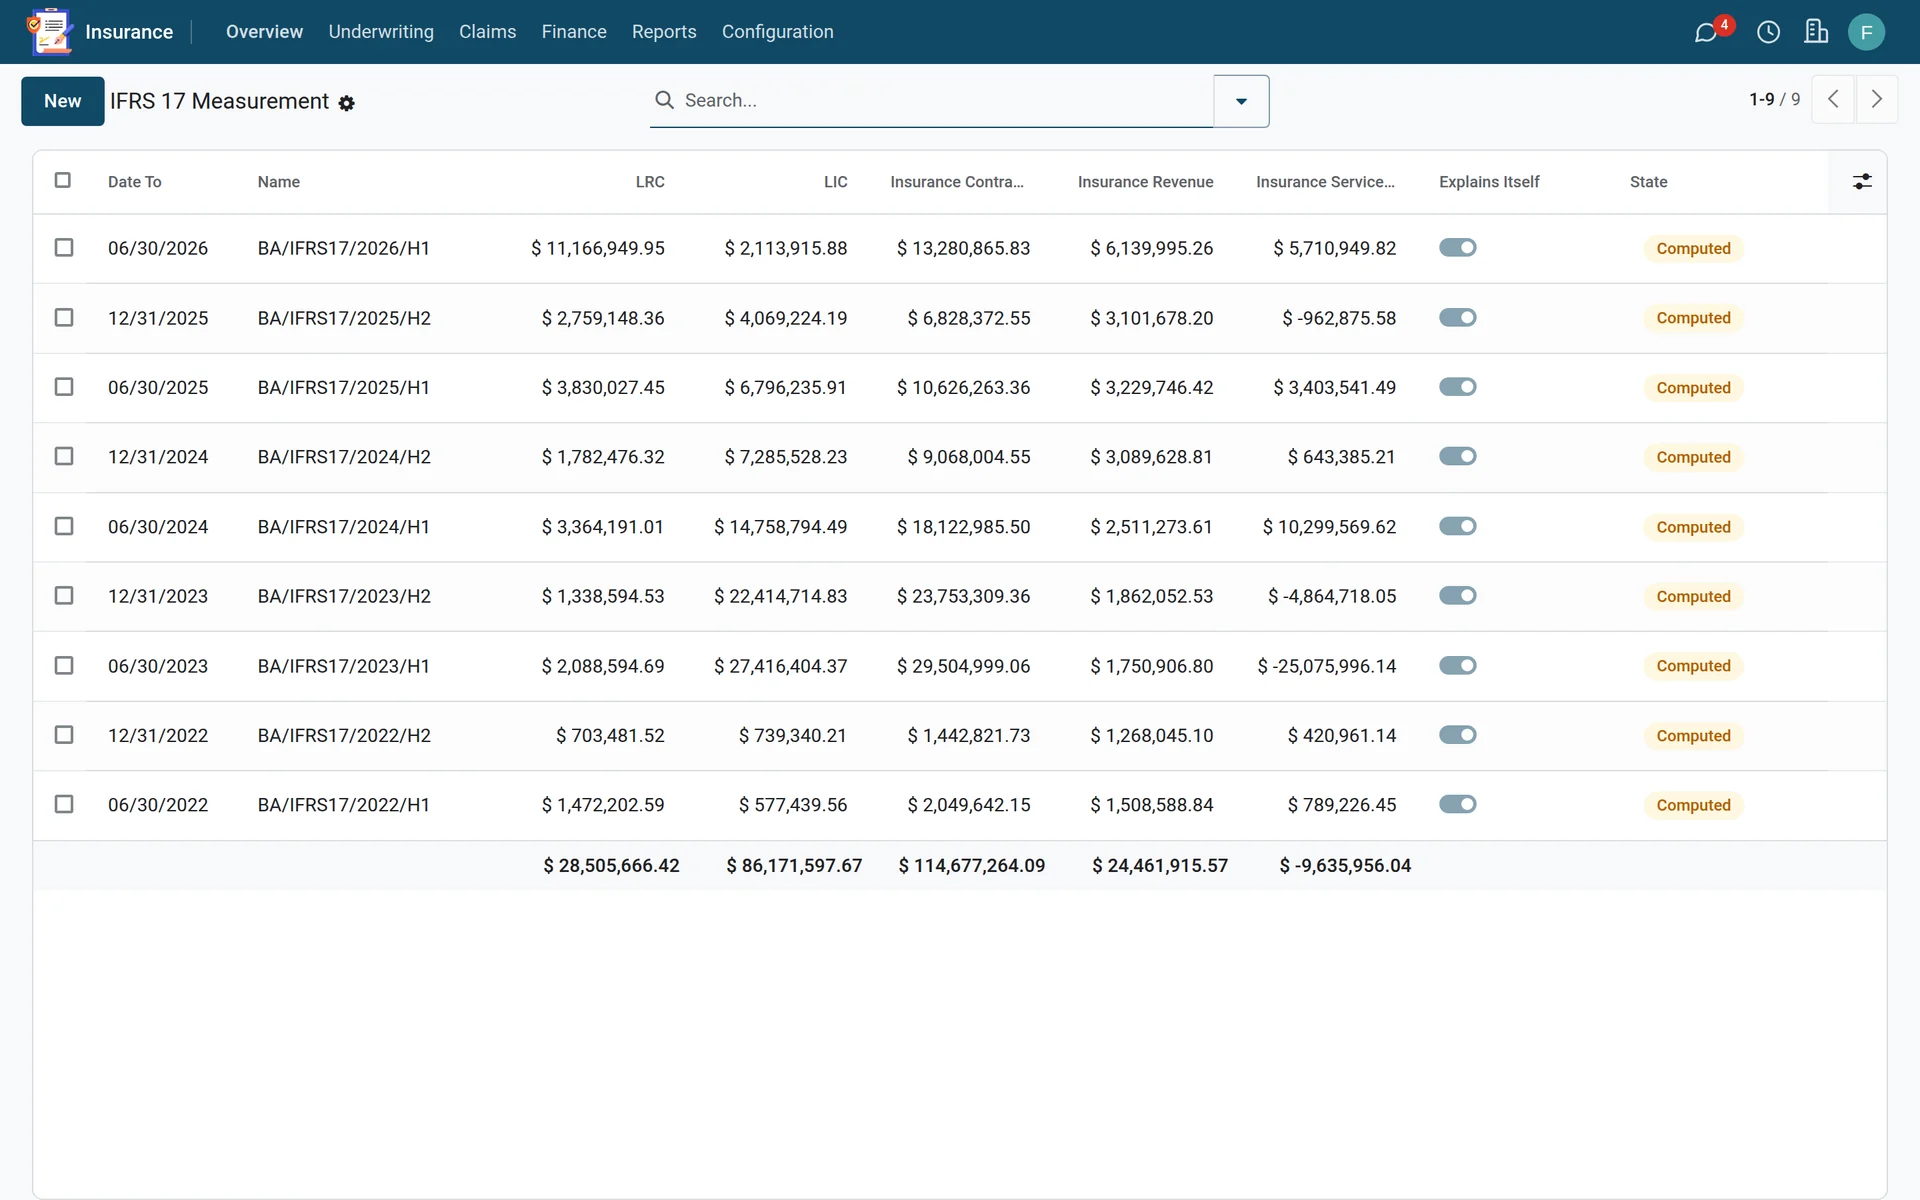
IFRS 17 measures groups of contracts, not a company: one portfolio, one annual cohort, one profitability bucket assessed when the contract is first recognised, and a contract never moves once it has joined a group. For each group the measurement rolls the liability for remaining coverage through premiums, acquisition cash flows deferred and amortised, insurance revenue and any loss component, and the liability for incurred claims through claims paid, case reserves, the reserving study's IBNR shared out on each group's incurred cost, and a risk adjustment. Every measurement states whether its movements explain the closing balance, and one that does not cannot be signed.
A measurement in one sentence
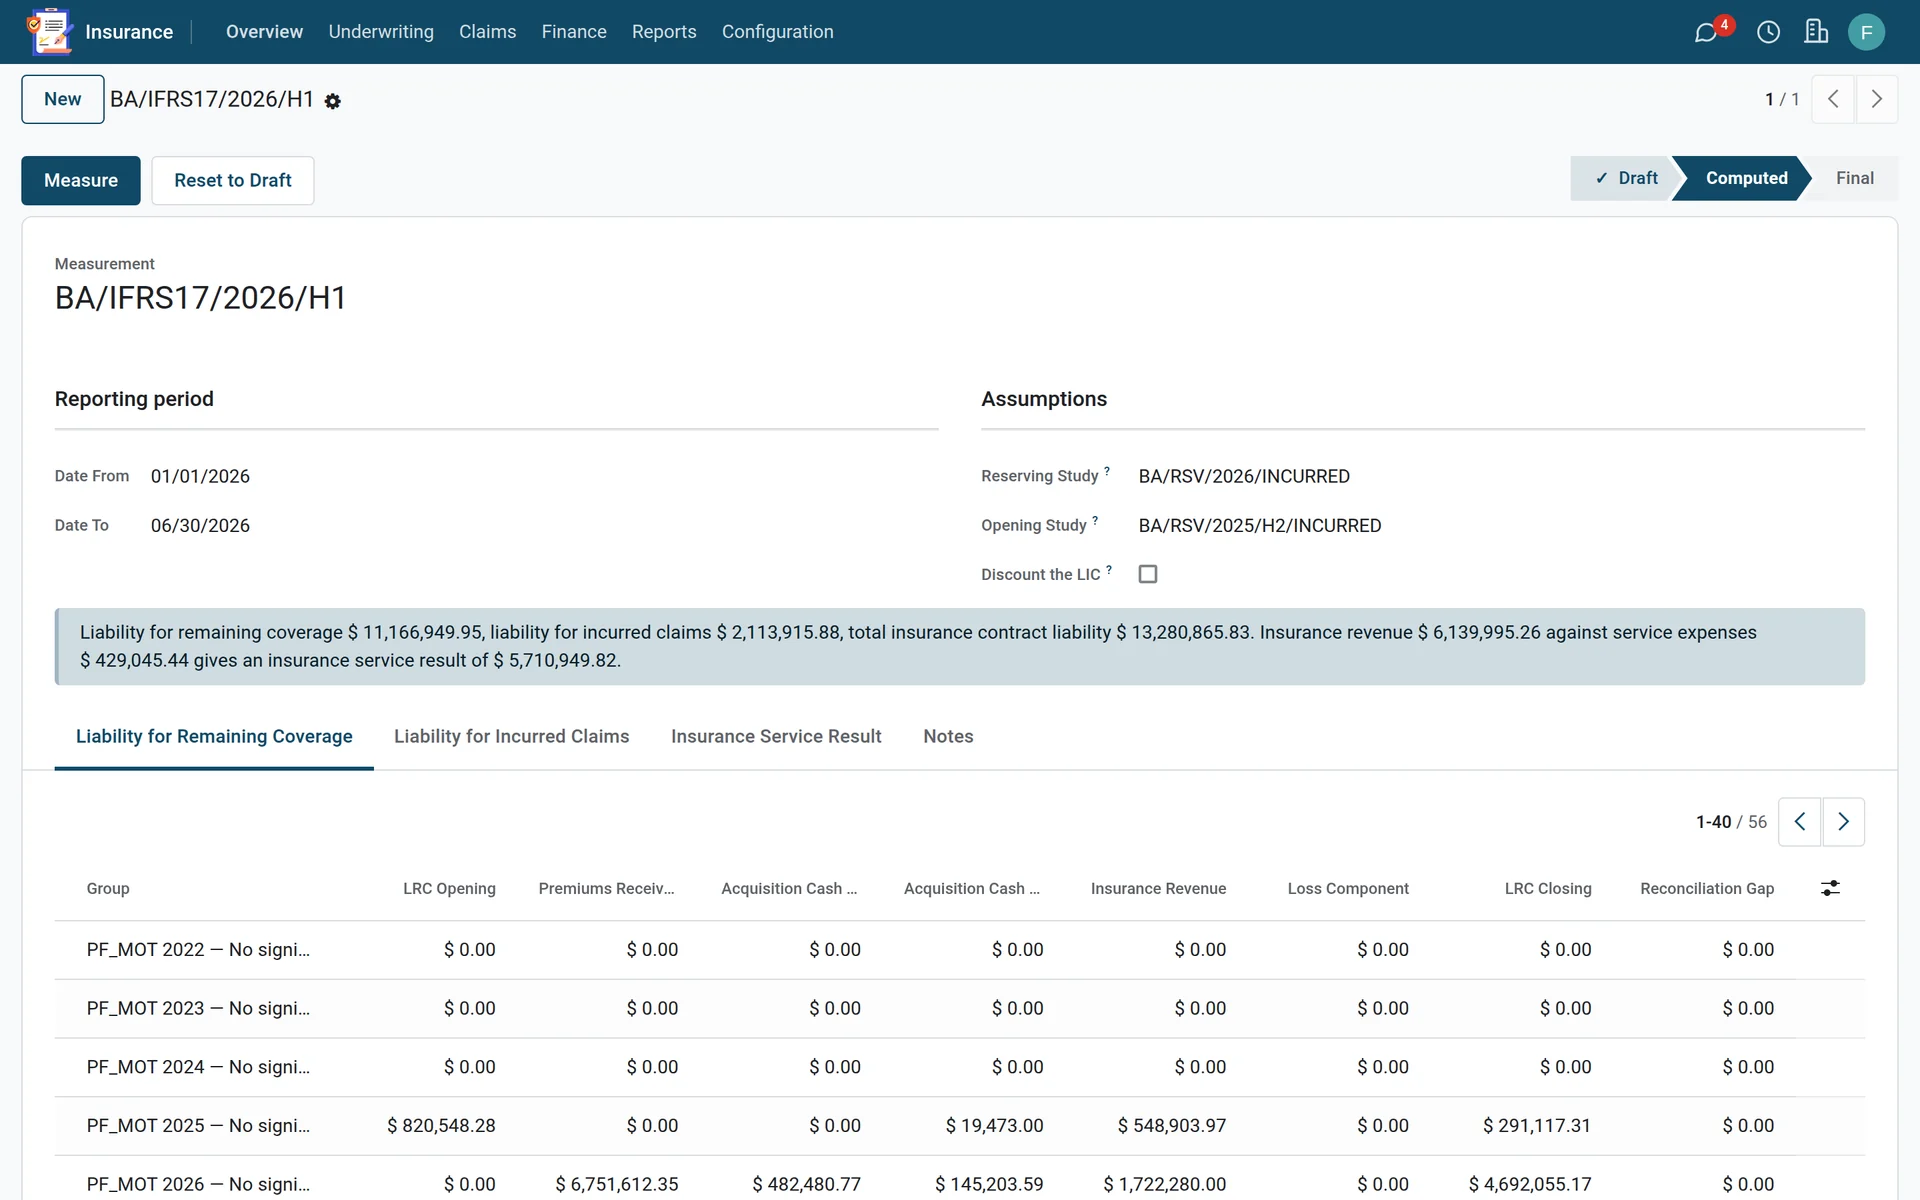
The reporting period, the reserving study and the opening study it is measured on, and the liability for remaining coverage, the liability for incurred claims, revenue, service expenses and the result written out.
Liability for incurred claims
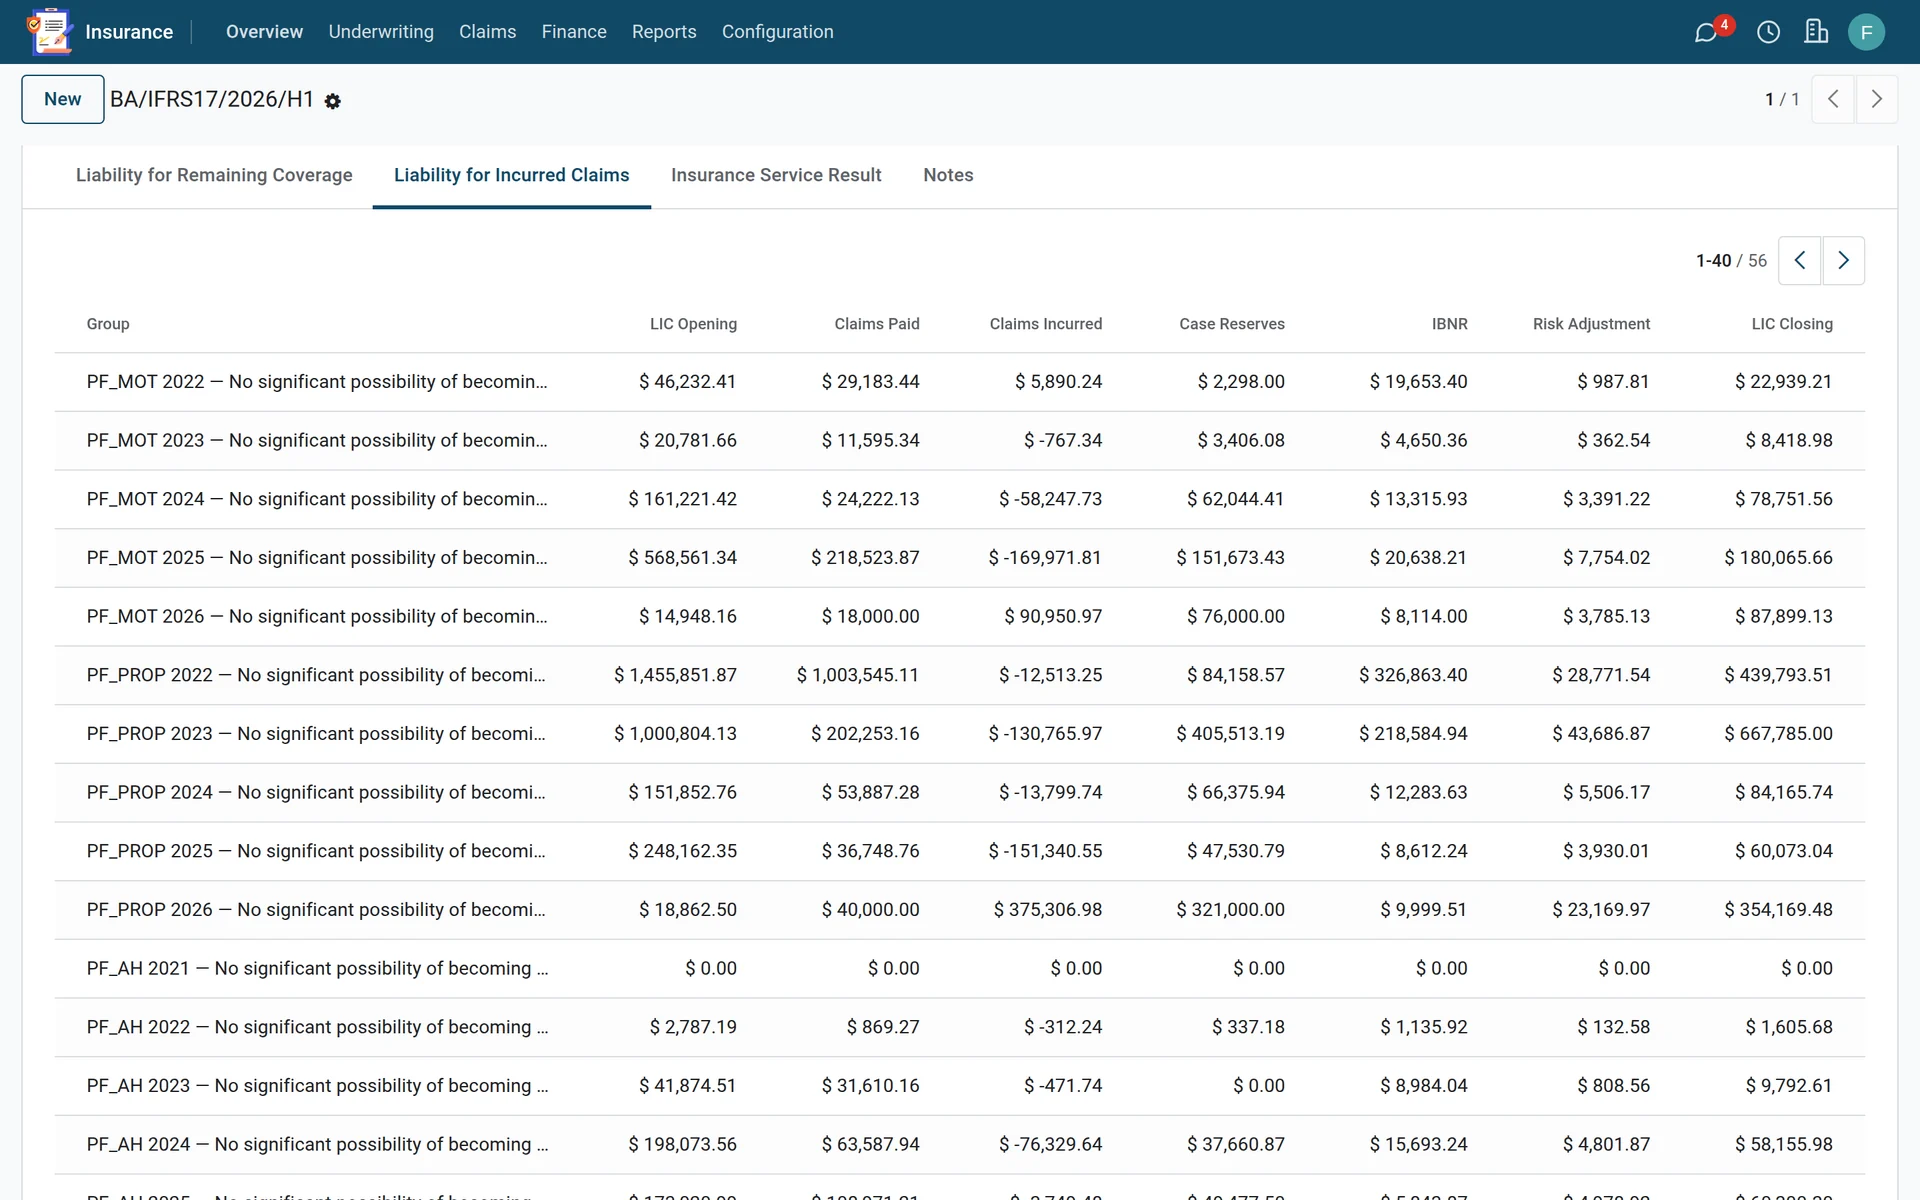
For each group of contracts: opening, claims paid, claims incurred, case reserves, IBNR, risk adjustment and closing.
Groups of contracts
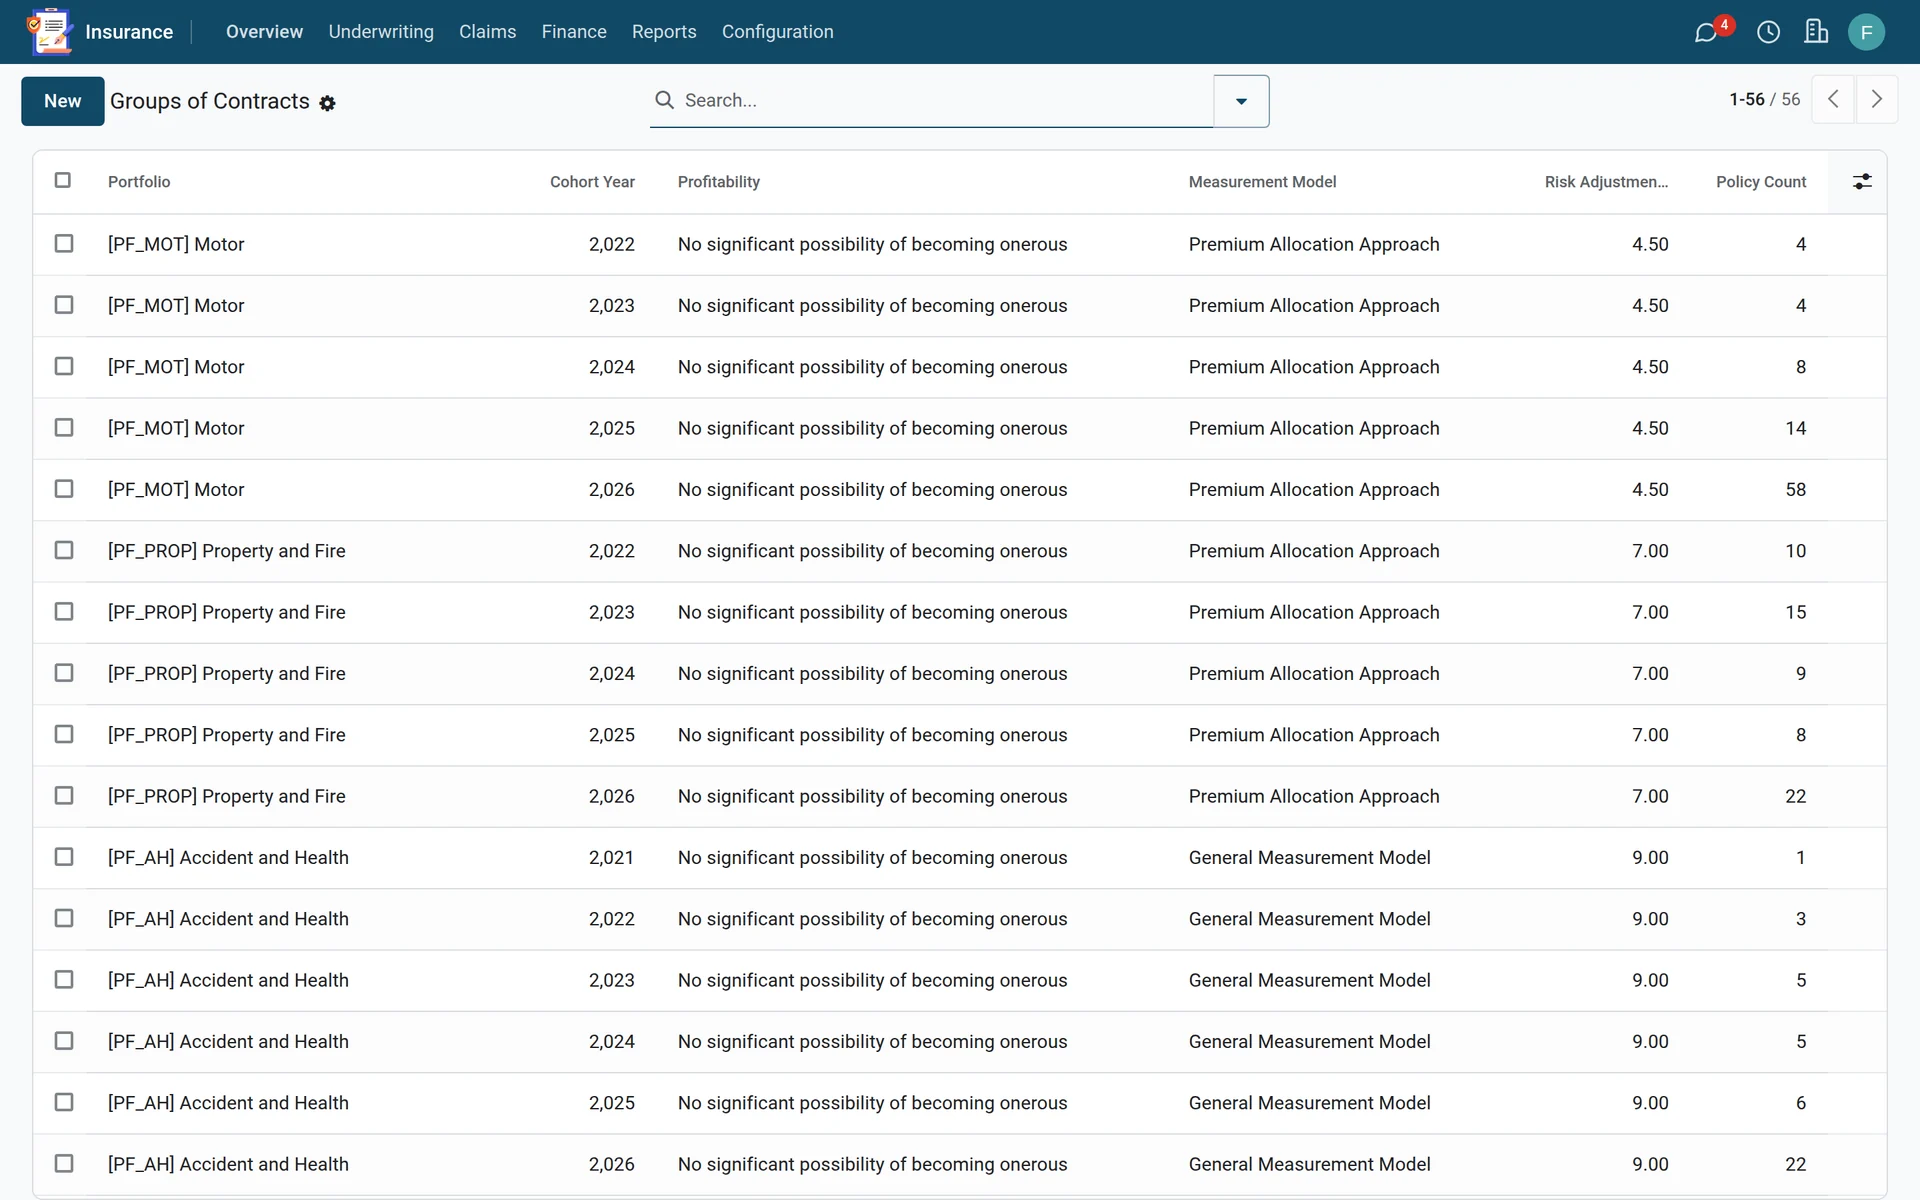
Portfolio, annual cohort and profitability for every group, with the measurement model and the risk adjustment it carries.
The liability for remaining coverage
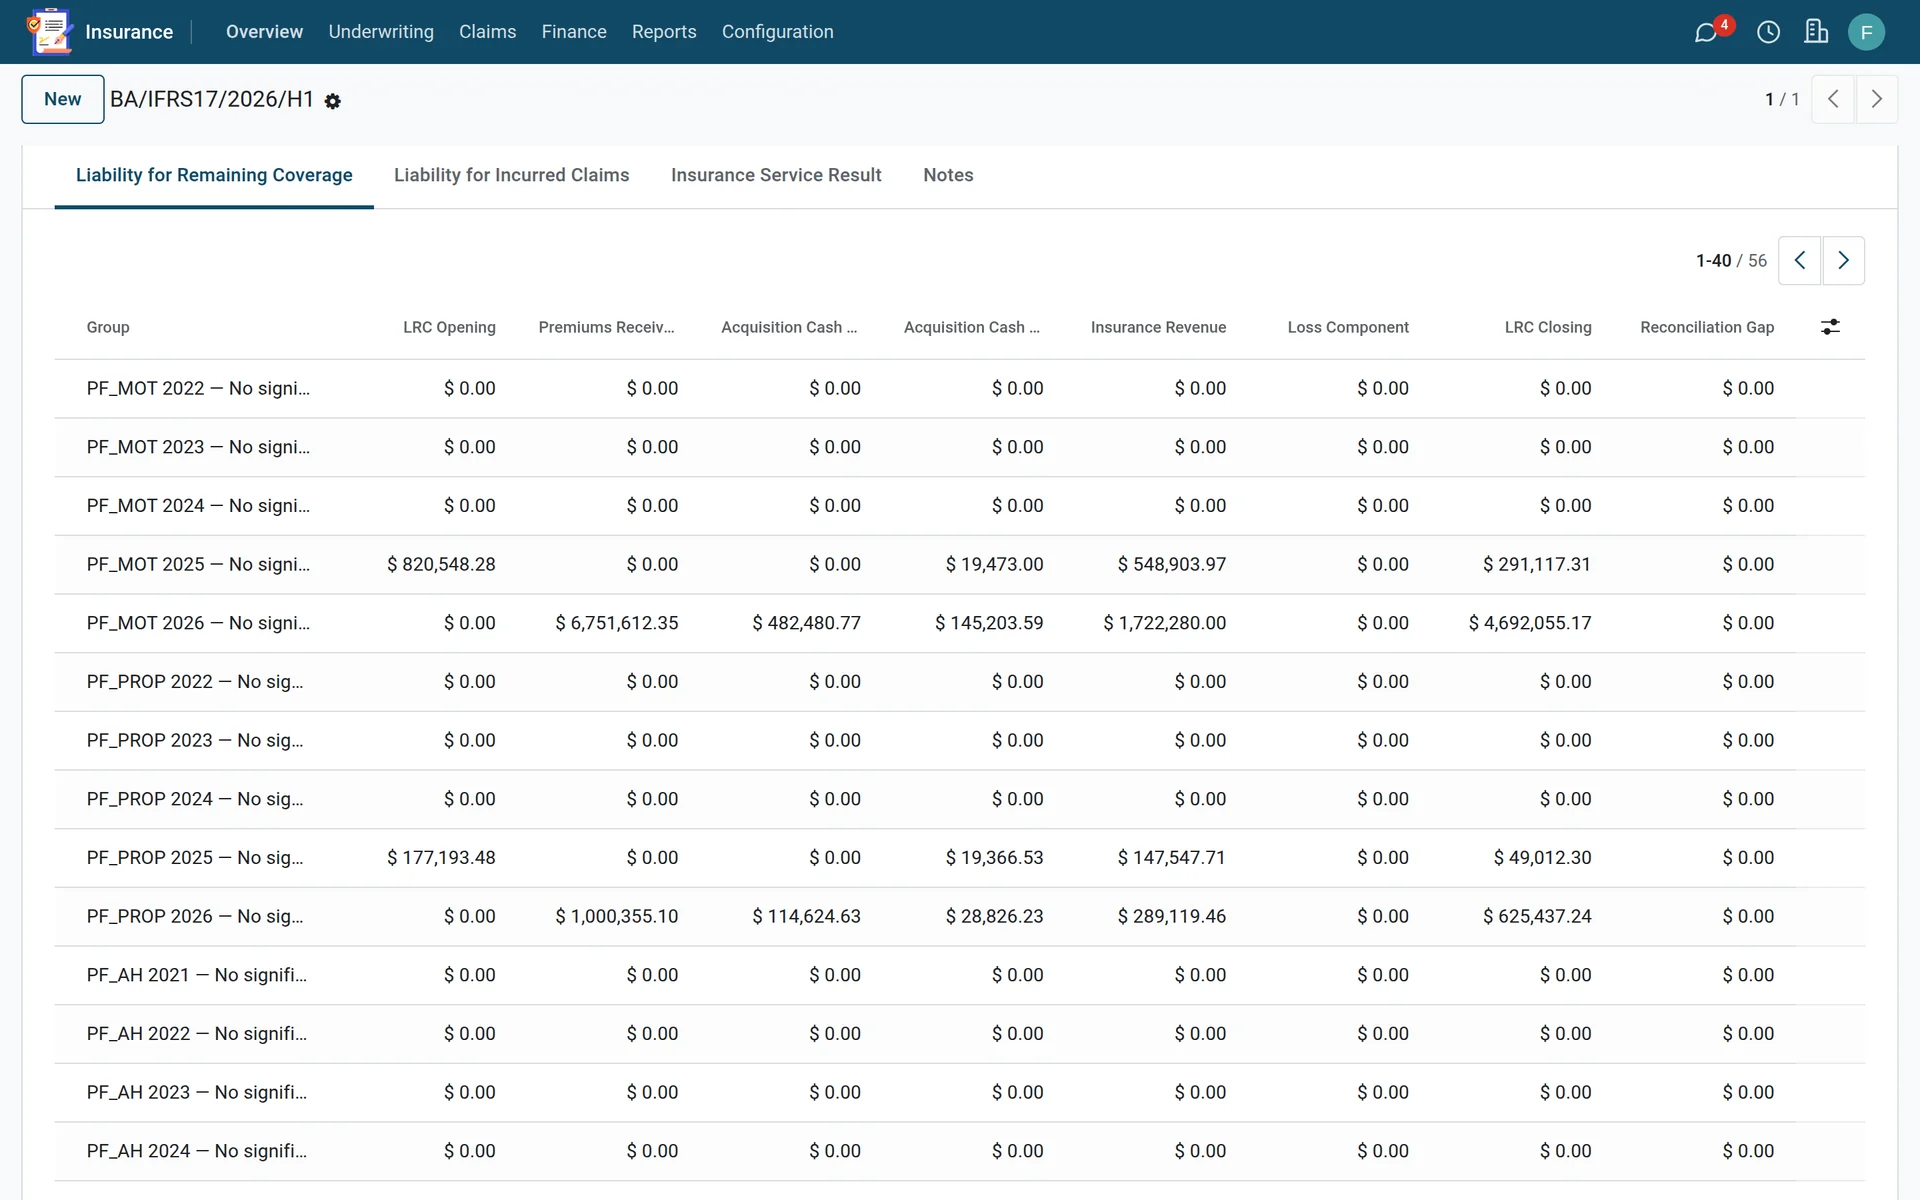
Opening, premiums received, acquisition cash flows deferred and amortised, insurance revenue and the loss component, rolled forward group by group.
The risk adjustment, set on the portfolio
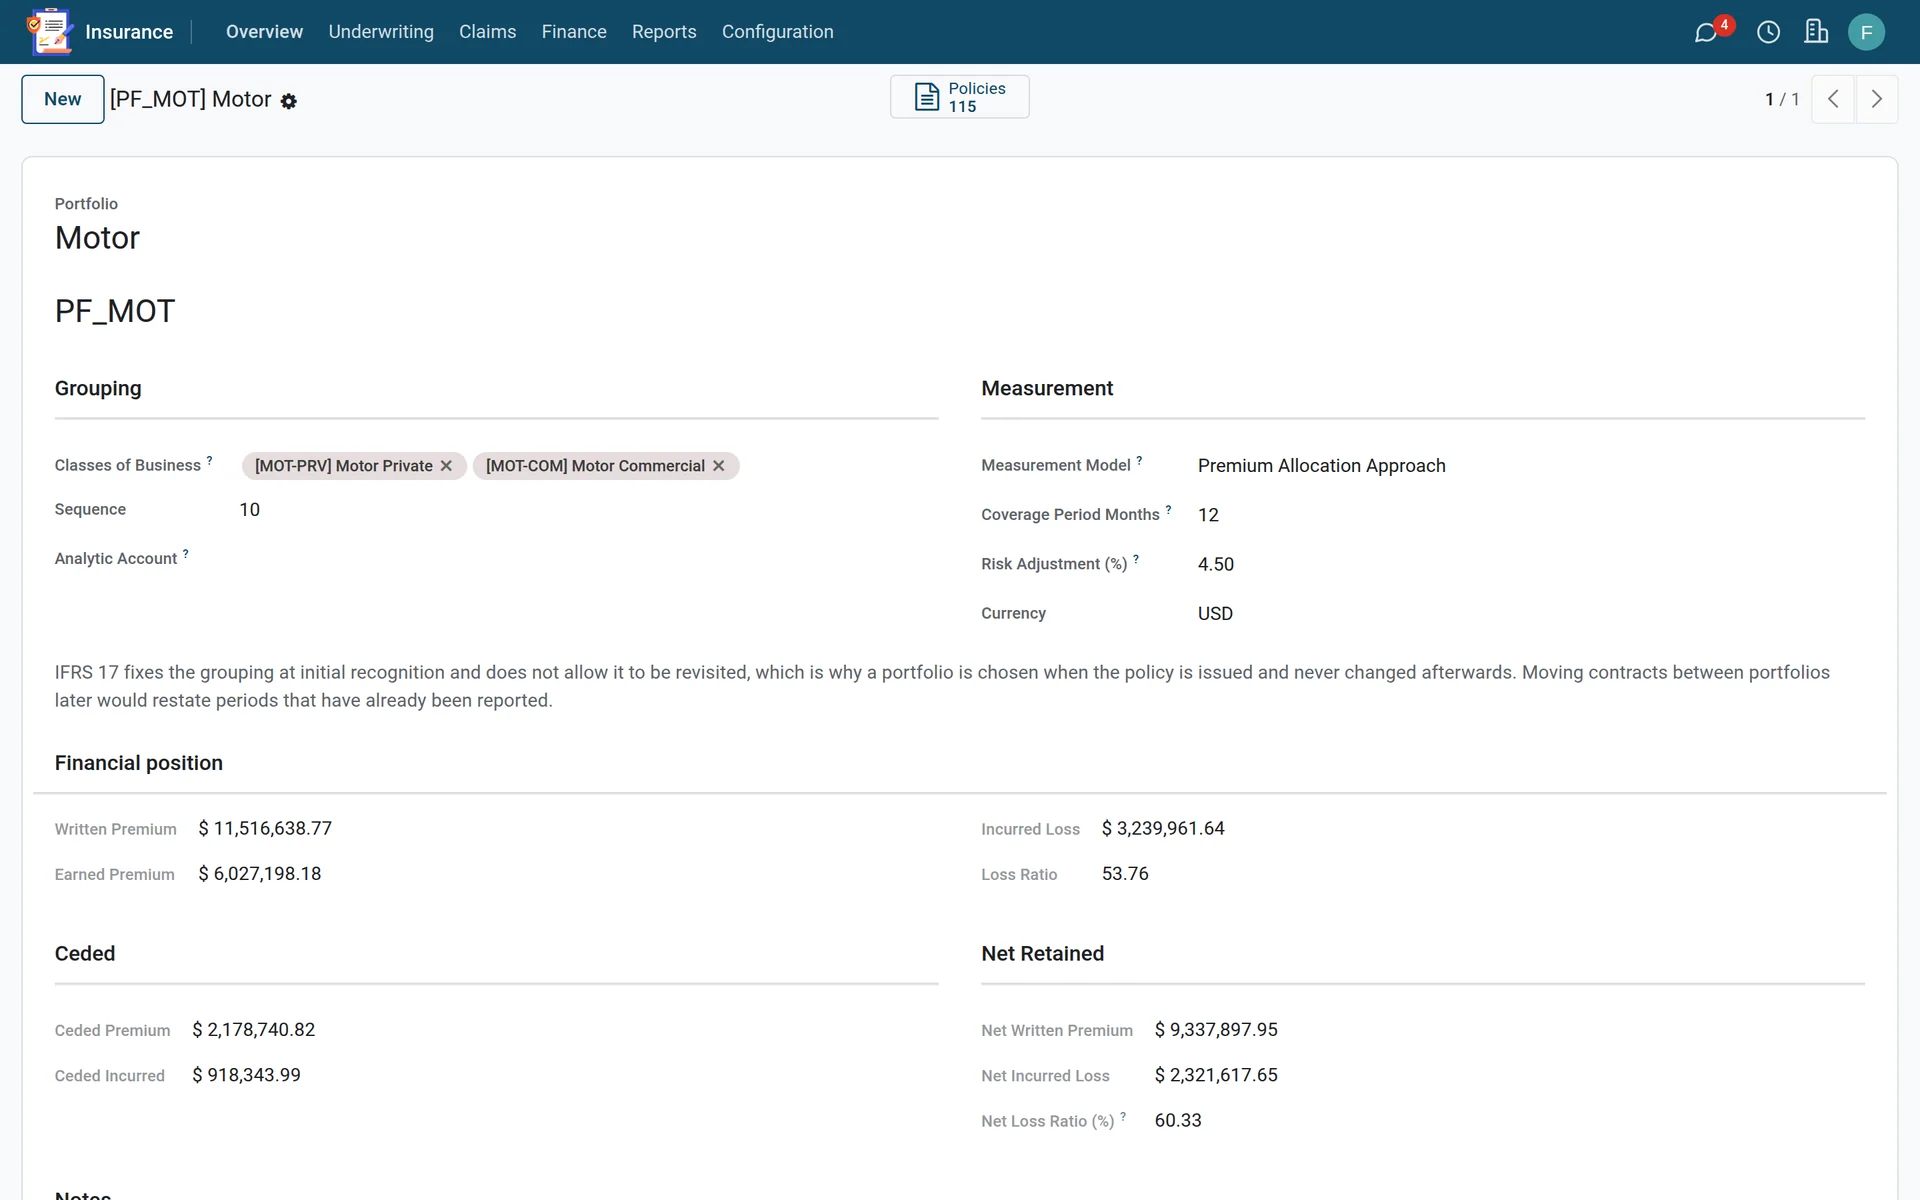
Set once per portfolio beside its classes, measurement model and coverage period, with the written, earned, ceded and net figures under it.